(News1. Report of April 26, 2026. Professor Sung Joo-ho's View of the Government Employees Pension Accrued Liability) "The Accrued Pension Liability Is Not a National Debt to Be Repaid Right Now — Korea's Aim Is the Preemptive Management of Fiscal Soundness" (Posted September 13, 2026)
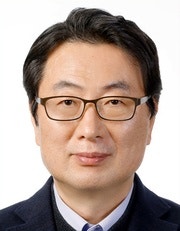
(This is an interview with Professor Sung Joo-ho,
whose perspective differs considerably
from the Pension Future Forum's.
One cannot help wondering how the International Actuarial Association
would assess this interview.)
[Interview]
Sung Joo-ho, Professor in the Department of Business Administration at Kyung Hee University…
former president of the Pension Association and of the Insurance Association
"An estimate of pension expenditure that takes no account
of employee and employer contributions…
substantially covered by pension revenue
The 'national liabilities' that the state must pay down in the future were found to have reached 2,771.6 trillion won last year, up 7.2% (185.9 trillion won) from the previous year.
This figure also includes the accrued pension liability of 1,344.4 trillion won, which is 31.5 trillion won higher than last year.
The accrued pension liability is an amount that estimates only the pension expenditure to be paid to retirees in the future, excluding the future pension revenue paid in by civil servants and military personnel.
Because that amount is included in national liabilities, concerns have also been raised that the money owed to retired civil servants could create problems for the state's finances.
Sung Joo-ho, Professor in the Department of Business Administration at Kyung Hee University, who has served as president of the Korean Pension Association, the Korean Insurance Association, and the Korean Risk Management Association, said in an interview with 'News1' on the 6th,
"The accrued pension liability is not a 'national debt' that must be repaid right now out of the public's taxes, so the public need not worry too much,"
he said, dismissing these concerns out of hand.
"Accrued pension liability, substantially covered by pension revenue over a long period"
Professor Sung noted, "From the standpoint of ordinary citizens, the accrued pension liability is so large that many are startled by it,"
and stated, "It needs to be understood not only that the accrued pension liability does not represent the pension amount payable immediately this year or a national debt, but also that over a long period it is substantially covered by pension revenue."
He said, "The accrued pension liability makes no calculation whatsoever of the pension revenue that will arise in the future, such as the employee contributions that serving civil servants pay each month and the pension contributions the state bears as employer,
and computes only the estimated pension expenditure that will arise over roughly the next 70 years or more for civil servants in service and pension beneficiaries as of the closing date of the accounts in each fiscal year, stated at its present value on that closing date."
He went on, "Many people think that the accrued pension liability, which accounts for about half of total national liabilities, is the country's debt — the national debt, that is — that must be borne in full out of the public's taxes, but
the accrued pension liability is an accounting construct whose payment date and amount are not fixed, unlike the national debt, whose repayment date and amount are."
Professor Sung said, "The accrued pension liability is simply a calculation of the estimated pension expenditure expected in the future, without taking into account pension revenue such as employee and employer contributions,
and because it is substantially covered by pension revenue over a long period, a situation in which the entire amount must be repaid right now out of the public's taxes does not arise."
"To preemptively manage the state's fiscal soundness,
included in 'national liabilities'"
Why, then, is the accrued pension liability included in 'national liabilities'?
With the enactment of the 'National Accounting Act' in 2009, the accrued pension liability became a mandatory disclosure in the settlement report from fiscal year 2011.
Professor Sung said, "The reason the accrued pension liability is included in national liabilities is to manage the state's fiscal soundness preemptively,"
and stated, "It is in order to identify and manage preemptively, from a long-term perspective, the government's comprehensive fiscal position and future fiscal risk."
He also explained that the concepts of national debt and national liabilities need to be looked at closely.
National debt is money borrowed from elsewhere when the government has to spend more than its budget, whereas the concept of national liabilities covers the national debt plus every sum the government will be responsible for paying in the future.
A liability, in particular, is an obligation borne by the accounting entity as a result of a past transaction or event, a present obligation for whose settlement an outflow or use of resources is expected in the future.
The explanation is that the accrued pension liability therefore differs from the national debt, whose repayment date and amount are fixed, and that, because pension revenue such as employee and employer contributions is not taken into account, it must be seen as different from the actual burden.
Professor Sung stated, "One may understand the intent to be this: for as much work as civil servants have done this year, the state as their employer has incurred a pension debt it must pay them later, so let this too be recorded as a liability."
"Accrued pension liability for fiscal year 2025,
a slowdown in the pace of increase"
He also said, regarding why only the Government Employees Pension and the Military Pension are included in the accrued pension liability, "Because the pension payment obligation of the state as employer has already arisen, it is recorded as a liability in the national accounts in accordance with the accrual-basis accounting principle."
The explanation is that, because the National Pension and the Private School Teachers Pension are not pensions the state provides acting as the employing entity but are intended to secure the public's old-age income as part of the state's social security policy, no accrued pension liability is recognized for them at the national closing of accounts.
Professor Sung said, "The accrued pension liability has been on a rising trend every year, and the natural increase, such as the growth in the number of pension beneficiaries due to aging, is the main driver of that increase,"
and stated, "In the case of the accrued pension liability for fiscal year 2025, it rose 2.4% from the previous year, which proved to be a slowdown in the pace of increase compared with the 6.8% growth rate in fiscal year 2024."
He said, "Because it is calculated through a long-term projection over a period of 70 years or more, it is also affected by changes in financial assumptions, such as the discount rate (the government bond interest rate) applied in converting cash flows that will arise in the future into their value at the present point in time,"
and added, "The fall in the present value of future pension amounts as the discount rate has risen, among other factors, is understood to have contributed to the slowdown in the pace of increase."