(PenN Mike, Including Pension Future Forum Comment) [Sim Yang-seop’s Straight Talk] The National Pension’s 182 Trillion Won Valuation Loss: Questions the Lee Administration Must Answer. More Important Than the Battle over Numbers Is the Basis for the Decision to Change Investment Principles (November 9, 2026)
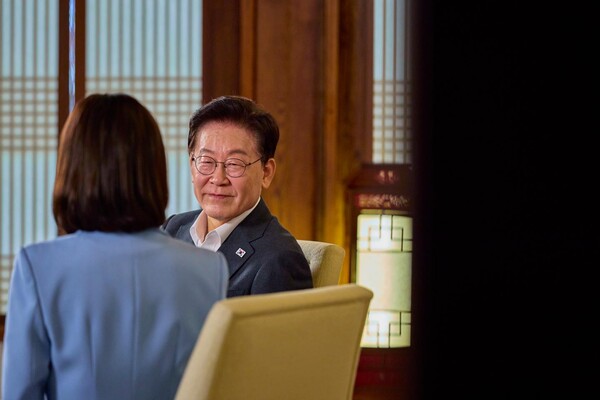
President Lee Jae-myung listens to the host’s question on the YouTube program “The President’s Y,” aired on the 5th. [Photo courtesy of the presidential office]
(The Pension Future Forum’s comment on this article:
The argument that “the 182 trillion won is not a realized loss but a decline in the valuation of some of its holdings” and nothing more,
as made by the government and the ruling party,
does not seem persuasive!
This is because, at the very time when structural reform of the National Pension was urgent,
the argument that the National Pension’s valuation gains had grown so large
that the pain of structural reform was no longer necessary—
that argument and that logic had first been put forward
by the government and the ruling party.)
On the 6th, the KOSPI fell more than 8% early in the session and was pushed below the 5,000 mark, and a circuit breaker was even triggered.
The index ultimately closed at 5,059.69, down 6.02%. This came just three weeks after “Black Thursday” on October 15, when it plunged 7.57% in a single day.
In the plunge on the 6th, pension funds, including the National Pension, made net purchases of only 288.5 billion won. That is about one-tenth of the approximately 2.77 trillion won in shares that foreign investors dumped. With the stock market collapsing, the buying by pension funds was not enough to hold up the market.
Why did the National Pension end up in a position where it was hard for it to step in aggressively and buy at low prices in such a plunge? As share prices rose, the National Pension sharply raised its target allocation for domestic equities and even deferred the rebalancing principle that required it to sell some of the stocks it held in excess. It put off selling even though it had the opportunity to sell stocks and secure investment capacity. As a result, it lost the capacity to buy stocks cheaply when share prices plunged. Had it sold some of its stocks during the rise and secured funds, it could have responded far more aggressively in the falling market.
According to figures compiled by the financial information provider FnGuide, the valuation of the shares of the 287 listed companies in which the National Pension holds a stake of 5% or more fell from 515.9293 trillion won at the end of June to 333.5330 trillion won on October 15. That is a decrease of 182.3963 trillion won, or 35.3%, in three and a half months. The figure does not yet even reflect the crash on the 6th of this month.
This “182 trillion won valuation loss” report card of the National Pension also became a point of contention at the parliamentary audit that ended in late October. To state the conclusion first, the wrong decisions driven by the government’s “political boosting of the stock market” not only severely constrained the National Pension’s ability to respond to the crisis but also ended up exposing the National Pension, on which the fate of the entire nation’s retirement savings rests, to excessive market risk.
Only three months earlier, the mood had been the exact opposite.
In the same tally, the valuation of the National Pension’s stockholdings rose by about 189 trillion won in the second quarter alone, the largest increase on record. In effect, it has given back almost all of that increase in a single quarter. It is only natural that more than 20 million insured people are asking, “Is my pension all right?”
The political battle over the pension funds’ helpless response to the stock market crash and over the decline in the National Pension’s valuation is also intensifying.
On November 6, Independent Representative Han Dong-hun criticized the government, saying, “The government did not prepare,” and “It raised the domestic equity allocation even further and went all in on ‘Samsung-Hynix.’”
He went on to demand a direct explanation from President Lee Jae-myung, saying, “We are now seeing the price of turning the market into a speculative gamble with the people’s retirement as collateral.”
Seoul Mayor Oh Se-hoon also posted a piece on Facebook on the 8th titled ‘Stock Gambling for the Local Elections: Stop Evading Responsibility Any Longer.’
Criticizing the government for “using the National Pension as seed money to raise the stakes,” he urged the President to apologize and to come up with measures to remedy the damage to investors.
The government and the ruling party rebutted them head-on.
On the 7th, Cho Kye-won, spokesperson for the Democratic Party of Korea, called Representative Han’s remarks “irresponsible agitation that stokes anxiety by turning the people’s retirement savings into material for political strife.”
His explanation was that the 182 trillion won is not a realized loss but a decline in the valuation of some of its holdings.
Lee Yong-woo, spokesperson for the ruling Democratic Party of Korea, also retorted to Mayor Oh on the 8th, “When share prices rise, it is ‘for the election,’ and when they fall, it is a ‘gambling den’?”
He stressed that raising the National Pension’s target allocation for domestic equities was a decision of the Fund Management Committee and that it was actually applied only after the local elections.
Earlier, Minister of Health and Welfare Jung Eun-kyeong had likewise explained at the parliamentary audit that “the 182 trillion won is the difference in total share value depending on the time of valuation,” and that it was not a realized investment loss.
If one touts the National Pension’s valuation gains as achievements while insisting that its valuation losses are not failures, that is nothing more than an unconvincing excuse.
Valuation gains and valuation losses alike are unrealized valuations.
The question that needs to be examined here lies elsewhere.
Why did the National Pension defer rebalancing and sharply raise its target allocation for domestic equities while share prices were rising? Did that decision not constrain its capacity to prepare for a plunge in share prices?
The government and the ruling party must not stop at responding to the political battle; they must disclose to the public the alternatives considered at the time, the risk analysis, and the basis for the decision.
182 Trillion Won: What Fell, and by How Much?
Of the 182 trillion won in valuation losses, 131.0971 trillion won, or 71.8%, came from two stocks: SK Hynix (74.2261 trillion won) and Samsung Electronics (56.8710 trillion won).
These two stocks also produced about 80% of the increase in valuation gains in the second quarter.
This means that, whether prices are rising or falling, the people’s retirement savings are deeply tied to two large-cap semiconductor stocks. It is said that valuation losses may be recovered if share prices rebound, but concentration risk does not disappear when share prices recover.
As Share Prices Rose, the Investment Principles Changed
The heart of the problem lies in the timeline.
On January 26, the Fund Management Committee raised the target allocation for domestic equities from 14.4% to 14.9%. Under the rules then in place, if the domestic equity allocation exceeded 17.9%, 3 percentage points above the target on a strategic asset allocation basis, the fund had to adjust its investment allocation by selling some of its domestic stocks that had risen sharply and buying other assets that had risen relatively less.
The Fund Management Committee, however, deferred this rebalancing until the end of June.
On May 28, just four months later, it raised the target allocation again, by 5.9 percentage points, setting it at 20.8%. It also temporarily widened the permitted range and decided to keep the 2027 target allocation at the same level.
Meanwhile, the actual allocation rose steeply. The National Pension’s domestic equity allocation, which at 11.5% at the end of 2024 was below the target at the time (15.4%), went to 18.1% at the end of last year and 21.4% at the end of January this year before soaring to 29.4% at the end of May.
What the government should have done at that point was to sell stocks in stages to realize valuation gains and secure the capacity to buy again in a crash.
Instead of selling, however, the government raised the target allocation for domestic equities.
The government explained that the measure reflected market conditions in which the actual allocation had far exceeded the target and was meant to improve long-term profitability and stability.
But this is a clear failure to keep to investment principles.
Far from trimming its stocks in a rising market, it raised its investment target to match holdings that had already grown.
Rather than managing the results according to its investment principles, it in effect rewrote the principles to fit the results.
The government describes this as “bringing the target in line with reality,” but the question it actually has to answer is why it raised the target allocation first instead of selling its excess stockholdings in stages.
Rebalancing is a safeguard in the National Pension’s asset management.
It is a device that maintains a set level of risk by trimming assets that have risen sharply and topping up those that have risen less.
Requiring mechanical selling when share prices rise is not an attempt to call the peak; it is a principle born of the humility to accept that no one can call the peak.
Of course, if the long-term outlook has changed, the target allocation may be adjusted.
But this change cannot escape the criticism that it was a decision that chased share prices that had already risen rather than one that reflected a change in the long-term outlook.
According to a 2014 study that analyzed 1,744 equity fund accounts, investors who chased and bought the funds with the highest returns performed 10–30% worse than investors who chose the funds with the lowest returns.
Strategic asset allocation and rebalancing were created precisely to prevent such behavioral biases of individuals.
The behavior of individual fund investors cannot be applied directly to the National Pension. But the decision to raise the target after share prices rose and to lock in next year’s target as well seems to presuppose an outlook that the bull market will continue.
If that is not the case, the government should present the long-term expected returns and the risk analysis that prove it was not chasing returns.
Who Bears the Cost of Reducing the Market Impact?
The National Pension is so large that the market shakes if it sells, while its asset allocation is distorted if it does not.
The so-called “Whale’s Dilemma” is real.
Academic empirical research, however, also shows another side. A 2014 empirical study found that the National Pension has played the role of stabilizing the market by increasing its net purchases when share prices fall and carrying out large-scale net sales when they rise.
Rebalancing—trimming when prices rise—was, in effect, the very mechanism that made the National Pension a market stabilizer.
If the allocation is filled to the brim during a rise, the capacity to step in and buy at low prices during a plunge shrinks accordingly.
That concern has become reality. According to the Korea Exchange, on the 6th, while foreign investors made net sales of 2.69 trillion won on the KOSPI market, net purchases by “pension funds and others,” which include the National Pension, came to only 287 billion won. That is 10.7% of foreign investors’ net sales. On October 15, when foreign investors sold 3.768 trillion won, net purchases by pension funds were 35 billion won, a mere 0.9% of foreign investors’ sales.
This is a far cry from the time of last year’s tariff shock.
From December 4, 2024, the day after martial law was declared, through April last year, pension funds made net purchases of about 8.35 trillion won, absorbing 43.6% of foreign investors’ net sales. In the plunge of March 2020 caused by COVID-19, too, they bought about 3 trillion won worth of shares in a single month.
What is the reality now?
Because the National Pension did not trim its domestic equity allocation in the rising market, it has run short of the ammunition it needs to serve as a “safety valve” precisely in the falling market.
Yun Suk-myung, Research Fellow Emeritus at the Korea Institute for Health and Social Affairs (KIHASA), pointed out, “The rebalancing principle was set in advance for times when judgment wavers with the market,
but by shaking it as needed, they have let even the golden opportunity for structural pension reform slip away.”
The management principles of the National Pension Fund are profitability, stability, public purpose, liquidity, sustainability, and independence of management.
Reducing the market impact is also an important consideration, but it must not override the goals of long-term profitability and risk management.
It could also have considered executing large-scale sales in installments over several days or capping the daily volume of sales.
In fact, on May 28, the Fund Management Committee revised the rules to reduce the maximum daily rebalancing volume.
Why, then, did it choose to defer rebalancing on January 26 instead of adjusting the volume of sales?
The government must explain how it compared the market impact and the risks of the two options.
That both decisions, in January and in May, were made ahead of the June 3 local elections also raises questions.
May 28, when the target allocation was raised to 20.8%, was six days before the election, and the day before that, May 27, saw the listing of high-risk leveraged products that track twice the daily price movements of Samsung Electronics and SK Hynix (it is precisely these products that have dragged our young people into the quagmire of debt-financed investing).
It is natural that suspicions arise that “retirement savings were mobilized to boost the stock market for political ends.” The responsibility for dispelling these suspicions lies with those who made the decisions.
It Cannot Be Brushed Off as a Mere Valuation Loss
The government argues that the 182 trillion won is merely a valuation loss during a stock market slump and not a loss that has actually been incurred. Through the end of August, the return on domestic equities reached 65.81%.
At that time, the National Pension Fund’s valuation gains were enormous. The valuation gains during the rise in share prices were also unrealized gains. To tout valuation gains as achievements when share prices rise and then to say there is no problem because they are only valuation losses when prices fall is a double standard.
What the Public Wants to Hear Is an Accountable Explanation of the Decisions.
The government must disclose analysis comparing the actual investment results with what would have happened had the existing rules been maintained.
It must be examined when and how much would have been sold under the existing rules, where those funds would have been allocated, and how large the market impact and transaction costs would have been.
The more fundamental problem is domestic concentration itself.
A 2017 study found that, once the effect of the National Pension’s enormous investment scale on domestic share prices is taken into account, concentrating investment in domestic equities is undesirable unless there is solid evidence that domestic stocks will deliver far higher returns than overseas stocks.
When the time comes when stocks must be sold to pay pensions, the domestic stocks it has piled up may, conversely, become a burden that drags share prices down.
The fact that 72% of this decline came from two semiconductor stocks shows that warning coming true ahead of time.
What the Public Needs to Know Is the Basis for the Decisions
There were reports that the Fund Management Committee’s January discussions on domestic equities would not be disclosed until 2030, and at the parliamentary audit in October, the ruling and opposition parties clashed over the submission of the minutes on the rebalancing deferral.
The Ministry of Health and Welfare, which oversees the National Pension Service, cites the fairness of fund management and the stability of financial markets as its reasons for not disclosing the permitted range and other details.
Of course, individual trading strategies need to be protected.
But the basis for the policy decisions that changed investment principles is a matter that the public, as the owner of the fund, needs to know.
Summary materials with sensitive figures redacted, the criteria for judgment, and the alternatives and risk factors considered could be disclosed first.
The greater a public fund’s influence, the greater its responsibility to be transparent about its management principles and direction.
There are five questions the Lee Jae-myung administration must answer.
First, what economic and stock market outlook served as the basis for deciding to defer rebalancing and raise the target allocation for domestic equities?
Second, how did it weigh this against alternatives such as phased, split selling?
Third, did it examine stock market crash scenarios and the risk of concentration in semiconductors?
Fourth, what dissenting opinions were raised within the Fund Management Committee?
Fifth, who will evaluate the performance after the decisions, by what criteria, and when?
Failure to answer these questions will lead to a collapse of public trust in the National Pension.
How Will the National Pension’s Independence Be Protected?
The National Pension Fund Management Committee is the highest deliberative and decision-making body, chaired by the Minister of Health and Welfare.
Although representatives of the insured and experts take part, it inherently carries the structural risk that the government’s economic policy goals may influence fund management.
The Ministry of Health and Welfare has said it will review the permitted range of the strategic asset allocation for domestic equities at the end of this year.
If so, this time it must set its principles straight instead of repeating stopgap measures.
When management principles are changed as an exception, the alternatives and risk analysis considered must be recorded, and the basis for the decision, excluding market-sensitive information, must be disclosed.
After a certain period, an ex post evaluation also needs to be made mandatory.
Standards for managing investment concentration in specific industries must be established, and the long-term asset allocation strategy, including diversified overseas investment, must also be reexamined.
Above all, institutional safeguards are urgently needed to protect fund management from the short-term economic and political goals of the administration in power. The National Pension is not a policy tool for propping up share prices but a fund that protects the people’s retirement.
If the suspicion that fund management is subordinated to the administration’s “political” goal of boosting the stock market is not dispelled, the government will lose the public’s trust.
In particular, the sentiment of the younger generation, which is sensitive to the sustainability of pension finances, may be the first to turn away.
What will follow is the departure of voluntary contributors and the spread of reluctance to pay contributions.
A collapse of trust in the National Pension is none other than the detonator of the administration’s collapse.
The National Assembly also has work to do.
The People Power Party is calling for a parliamentary investigation to determine whether there was political interference in the process of deferring the National Pension’s rebalancing and expanding its domestic equity allocation.
Its position is that it will examine the Fund Management Committee’s decision-making process and the adequacy of its risk management and, if necessary, even push for a special counsel.
In response, the ruling party, which holds a stable majority of the seats in the National Assembly, must not stop at dismissing this as a “political offensive” but must cooperate with public scrutiny.
Was it not the ruling party that, just before the June 3 local elections, advertised “KOSPI’s Dream Index: Breaking 6,000” on Democratic Party lawmakers’ banners all across the city centers of the Seoul metropolitan area?
Was it not the ruling party that sank countless young people deep into the swamp of “debt-financed investing”?
Outstanding margin loans, used to buy stocks with borrowed money, stood in the 28 trillion won range as of the 5th, 1.8 times the level at the end of 2024.
The financial authorities temporarily eased the rules on forced liquidation from the 9th, but the same measures had little effect in 2020 and 2022 as well.
Transparency is the way to rescue the National Pension from political strife. If the basis is disclosed, the opposition will criticize the government and the ruling party on the basis of concrete supporting materials instead of vague suspicions, and the government can be judged by its process rather than its results.
The National Pension is not a stage for an administration to pile up achievements but a storehouse on which the people’s retirement depends.
It is the front line of realizing the “welfare” that progressive administrations repeat like a mantra.
Share prices may rise again, and the 182 trillion won valuation loss may someday be made up.
But principles and trust, once broken, do not rebound as easily as share prices.
The government must answer not by explaining away the numbers but by disclosing the basis for its decisions.
Sim Yang-seop (Ph.D. in political science; former Chosun Ilbo reporter; currently head of the Education Community for North Korean Defector Youth)