(Dong-A Ilbo) Greece and Portugal Achieve Fiscal Surpluses Through Harsh Structural Reform (November 9, 2026)
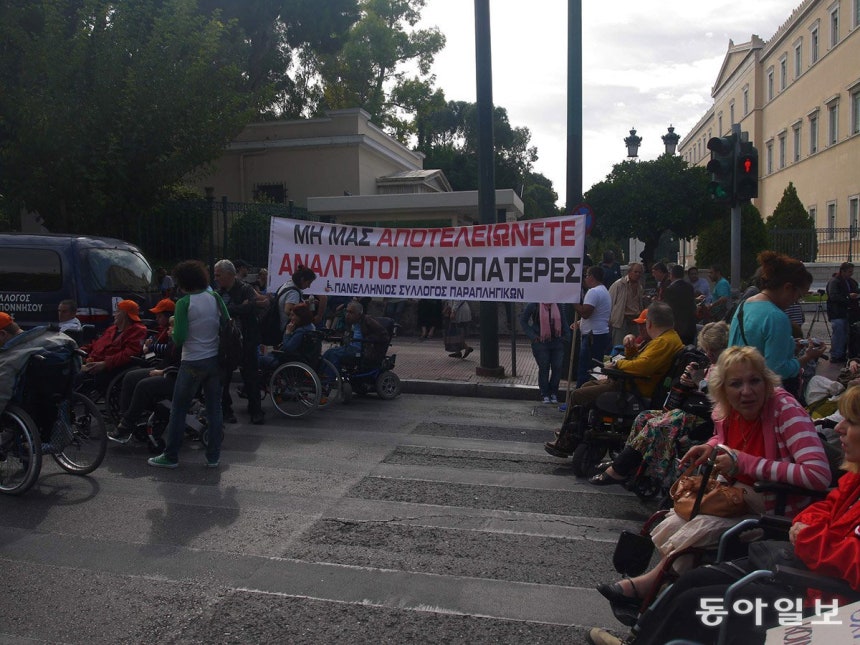
2015. 10. 21. On the road in front of the main gate of the Hellenic Parliament in Athens, Greece, some 200 people with disabilities stage a street protest, chanting, “Stop the disability pension cuts.” Dong-A Ilbo DB
Structural reform has split the eurozone’s fortunes
The PIIGS, once “Europe’s problem children,” transformed
Portugal pushed back pensions in line with life expectancy
Greece cut civil servants’ wages and pensions
While France is in turmoil over chronic fiscal deficits and mass protests against an austerity budget, the fiscal situation of some southern European countries once labeled “Europe’s problem children” is improving. Portugal, Greece, and others that embarked on harsh austerity and pension reform after the fiscal crisis have swung into fiscal surplus.
According to Eurostat, the statistical office of the European Union (EU), and other sources on the 8th, France’s fiscal deficit last year came to 5.1% of gross domestic product (GDP). The share, which was 2.6% in 2017 when French President Emmanuel Macron began his first term, rose to 5.1% last year and is projected to climb to 5.4% this year. Although pension and medical spending is rising with population aging, pension reform to raise the eligibility age has met resistance and effectively stalled, prompting assessments that France has sunk to the status of “the sick man of Europe.”
By contrast, the so-called “PIIGS” (Portugal, Ireland, Italy, Greece, and Spain), the epicenter of the European fiscal crisis in the early 2010s, appear to have partly succeeded in improving their fundamentals through painful structural reform. Greece and Portugal in particular posted fiscal surpluses last year equal to 2.0% and 0.7% of GDP, respectively.
After receiving a bailout from the International Monetary Fund (IMF) amid a sovereign default crisis in 2010, Greece embarked on steep cuts in government spending, including reductions in civil servants’ wages and pensions. It also pursued economic reforms, such as easing labor market regulations and selling state assets to the private sector. As economic recovery and fiscal improvement continued thereafter, its national debt ratio fell 18.6 percentage points in two years, from 164.0% in 2023 to 145.4% last year.
Portugal reduced the fiscal burden of population aging by raising the pension eligibility age. After receiving a 78 billion euro bailout in 2011, it cut government spending and eased labor market regulations. In 2014 it raised the pension eligibility age from 65 to 66 and introduced a system that delays the eligibility age by about eight months for every one-year increase in life expectancy. As a result, the eligibility age is 66 years and 9 months this year and will be 66 years and 11 months next year. Helped also by economic recovery, its national debt ratio fell from 111.2% in 2022 to 89.2% last year.
Spain strengthened its laws and institutions to keep government spending from swelling indiscriminately. In 2011 it amended its constitution so that the fiscal deficits of the central and regional governments would not exceed the EU limit, and the following year it also enacted a law preventing government spending from growing faster than the trend rate of economic growth. The aim was to keep the government from expanding spending excessively even when an economic boom brings in abundant tax revenue. Spain’s fiscal deficit last year was 2.4% of GDP, about half that of France (5.1%).
Analysts say that, with pension and welfare spending also rising in Korea as the population ages, Korea needs to look to the southern European countries that cut spending and undertook reform after the fiscal crisis. The government plans to create a “Future Response Fund” using the tax revenue boosted by the semiconductor boom. When its corporate tax revenue surged in 2023, Ireland decided to set aside 0.8% of GDP every year from 2024 to 2035 in the Future Ireland Fund to prepare for future spending on pensions, medical costs, and other items that will grow with population aging.
Sejong — Reporter Lee Sang-hwan [email protected]