The Automatic Adjustment Mechanism — Young People Must Be Told of Its Benefits [Contributed Article / Yun Suk-myung] (September 22, 2024)
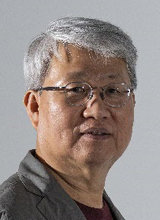
Yun Suk-myung, Research Fellow Emeritus, Korea Institute for Health and Social Affairs
The system overhaul plan of the National Assembly Special Committee on Pension Reform, which came close to a deal in May, can hardly be regarded as a reform plan. This is because the size of the burden shifted onto future generations grows as time passes.
The reason I judge the 21st National Assembly’s discussions and this administration’s pension reform plan to be different is the difference in the priorities of pension policy.
The pension policy goals that President Yoon Suk-yeol mentioned in his policy briefing were, in order, sustainability, intergenerational fairness, and old-age income security.
This differs in character from the 21st National Assembly’s pension discussions, which made old-age income security the top priority.
According to the National Pension financial projection reflecting the 2023 population projection, a pension plan with a 40% income replacement rate would require collecting contributions of 19.7% in order not to shift the burden onto later generations.
This means that 19.7% must be collected in order not to increase any further the 1,700 trillion won in unfunded National Pension liability that the Ministry of Health and Welfare reported to former National Assembly Speaker Kim Jin-pyo.
Unfunded liability is the amount by which assets fall short of the pension amounts that have been promised.
When a pension system is in balance between contributions and benefits—that is, when the money received and the money paid in are balanced—the “equivalence whereby 1 percentage point of contributions corresponds to 2 percentage points of the income replacement rate” applies.
At a 40% income replacement rate, a 19.7% contribution rate is the balance between contributions and benefits, and raising the income replacement rate by a further 4 percentage points would require raising contributions by 2 percentage points more, to 21.7%, to reach that balance. This is the condition under which the 1,700 trillion won in unfunded liability would stop growing.
The “44% income replacement rate–13% contribution rate” plan, which came close to a deal in May, falls 8.7 percentage points short of the contribution rate that balances contributions and benefits.
This means passing on to later generations a debt roughly equal to the total National Pension contributions collected each year (about 58.4 trillion won).
Despite this reality, it was misrepresented as a fiscal stabilization plan on the grounds that it extends the fund depletion date by a few years. It is a typical case of deceiving the public by exploiting complex pension concepts.
The government’s “42% income replacement rate–13% contribution rate” plan also falls 7.7 percentage points short of the balancing contribution rate. The automatic adjustment mechanism was proposed to address this. It is a method that links changes in the environment, such as rising life expectancy and falling birth rates, to the operation of the pension.
The problem is that, by building the frame of an “automatic cutting mechanism,” public opinion is being shaped so that even young people, who would in fact benefit most from the automatic adjustment mechanism, view it negatively.
The automatic adjustment mechanism need not be an “automatic cutting mechanism”; it could become an “automatic maintenance mechanism” or even an “automatic increase mechanism.” This is because extending the mandatory contribution age, currently 59, to 64 could increase the income replacement rate by 13%.
If a “re-employment after retirement system” is introduced through labor market reform, new hiring of young people and continued employment of older people become possible at the same time. Through five additional years of earned income and additional National Pension coverage, old-age income could increase dramatically.
While 70% of the member countries of the Organisation for Economic Co-operation and Development (OECD) have already introduced an automatic adjustment mechanism, we merely criticize it as premature, citing the large gap from the balance between contributions and benefits.
For us, who have missed the golden opportunity for pension reform by failing to raise contributions by even 1 percentage point over the past 26 years, how much more time would it take for “premature” to be resolved?
It brings a sense of déjà vu of the logic used to oppose the Roh Moo-hyun administration’s 2007 reform plan, which proposed “raising contributions to 12.9% by 2018.”
This is why it must be explained well that the automatic adjustment mechanism is the minimum mechanism that will keep us, who have already missed the golden opportunity for reform, from mutual destruction.
Yun Suk-myung, Research Fellow Emeritus, Korea Institute for Health and Social Affairs