(Incheon Ilbo Report, July 7, 2026) Park Sun-won Introduces National Pension Act Amendment… Will the National Pension's Role Change in the 'KOSPI 8,000 Era'? (Posted October 18, 2026)
[In July 2026, through a member of the National Assembly
from the ruling Democratic Party,
a bill to suspend National Pension rebalancing
was introduced.
(At a Fund Management Committee meeting in the first half of 2025,
the 2026 figure had already been finalized.)
The National Pension's
domestic equity investment ratio
was raised, through the sudden
convening of Fund Management Committee meetings,
on as many as two occasions.
Such were the steps taken.
Then, in July,
a bill to suspend rebalancing
was introduced.
It is on this basis that the Pension Future Forum
judges that the political sphere
has intervened excessively
in the management of the National Pension Fund.
We post the related article below.]
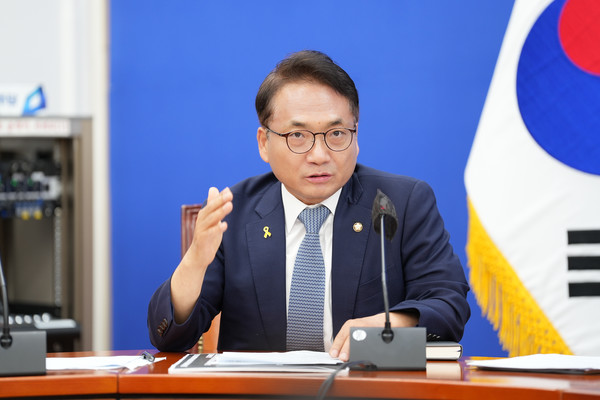
Representative Park Sun-won (Bupyeong-eul) of the ruling Democratic Party of Korea announced on the 7th that Park had introduced, as lead sponsor, a bill that would allow, in cases of sharp fluctuations in the financial or foreign exchange markets,
the National Pension Fund's target allocations by asset class to be adjusted
and the selling and buying of assets to reach those targets to be temporarily suspended —
a 'Partial Amendment to the National Pension Act.'
The core of the amendment is that, at a time when the recent surge in the domestic stock market has made it increasingly likely that the National Pension's domestic equity holdings will exceed their target,
it creates a legal basis for suspending for a set period so-called 'mechanical rebalancing,' in which large volumes of stock must be sold to meet the target allocation.
The current National Pension Act requires the fund to be managed by setting target allocations each year for each asset class, such as domestic equities, overseas equities, bonds and alternative investments.
But when share prices surge, the domestic equity allocation naturally grows, and to bring it back to the original target the National Pension must sell a considerable amount of domestic equities.
Concerns have been raised continually that if the National Pension, the country's largest institutional investor, sells on a large scale within a short period, it could deal no small shock to the stock market.
Accordingly, Representative Park added a new provision allowing the Minister of Health and Welfare, after deliberation by the National Pension Fund Management Committee, to adjust the target allocations and permitted ranges by asset class, or to temporarily suspend the selling and buying of assets to reach the target allocations, in cases where the financial or foreign exchange markets fluctuate sharply.
Such measures, however, are permitted only to the extent that they do not undermine the long-term stability and profitability of the National Pension, and the bill also provides an ex post control mechanism by requiring a report to the competent standing committee of the National Assembly after implementation.
The bill draws attention in that it goes beyond a mere change in management technique and also dovetails with the capital market revitalization policy pursued by the Lee Jae-myung administration.
The government has held out the prospect of a 'KOSPI 8,000 era' through the Commercial Act amendment, enhancing corporate value and resolving the 'Korea discount,' but a structural problem has been pointed out: the higher the stock market rises, the more the National Pension's mechanical selling holds back the market's upward momentum.
The amendment is essentially an attempt to ease this conflict institutionally.
On the other hand, controversy over the National Pension's independence is also expected.
Since the National Pension is a long-term investment institution managing the public's retirement savings, debate is likely to continue over whether it is appropriate to adjust the timing of its selling according to government policy.
Some also point out that, because the requirement of 'sharp fluctuations in the financial or foreign exchange markets' is somewhat abstract, more specific criteria should be set out in the enforcement decree.
In the end, the amendment is significant in that it has opened a new policy debate over whether to regard the National Pension simply as a pension fund investment institution, or also to give it the role of an institutional safety valve for capital market stability.
In the National Assembly's deliberations ahead, the question of where to strike the balance between market stability and the National Pension's independence is expected to emerge as the key point of contention.
https://www.incheonnews.com/news/articleView.html?idxno=438000